Argentina · Energy
Vista Oil & Gas: Can it keep going up?
Miguel Braun · Nov 6, 2022 · 3 min read
Vista is a company dedicated to Oil & Gas production in Argentina, its main asset being the wells it has in Vaca Muerta, Neuquén. They recently released the results for the third quarter of 2022, which were really very good.
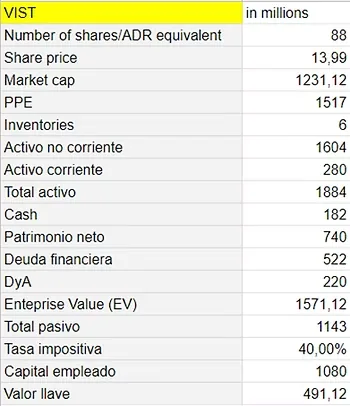
Key facts of Q3:
- The company currently exports 50% of its oil production, which allows it to have "dollarized" income in an unstable economy like Argentina.
- Oil exports +446% YoY
- Revenues +91% YoY
- Net income +325% YoY
Numbers:
As we can see, Vista increased all its lines from one year to the next. This was due to higher production and a higher average price on sales, taking advantage of the worldwide rise in oil and natural gas prices from the war in Ukraine.
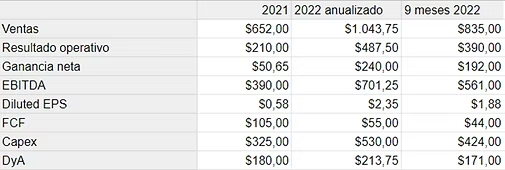
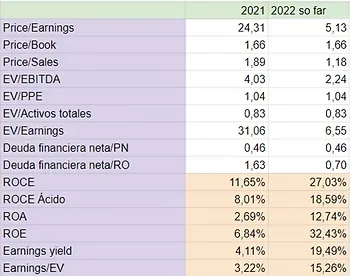
This caused Vista's valuation multiples to compress sharply (P/E from 24 to 5), and its profitability ratios to increase considerably.
Today the company generates 20 USD of profit for every 100 you pay to become a shareholder. It also has very good returns on capital employed, assets and equity.
Doing a super conservative DCF, assuming the company will never grow its free cash flow again and discounting the future cash flows at a 10% rate, we get that the company should be worth 1,500 million USD, which represents 22% upside over the current price. And this assuming the company's free cash flow won't grow for the next 20 years, which is quite unlikely given that Vista will benefit a lot from the production of the new pipeline, which will allow it to export more production.
For this DCF analysis I take the free cash flow as given by the company, which calculates it using Operating Cash Flow minus Investing Cash Flow.
"Capex during Q3 2022 was 162.8 $MM (in the first 9 months of the year it was 424 million USD in total, which annualized gives us 530 million). The Company invested 106.4 $MM in drilling, completion and reconditioning of shale wells, 3.8 $MM in drilling, completion and reconditioning of wells in conventional assets, 31.2 $MM in development facilities and 21.3 $MM in studies, projects and other infrastructure."
Conclusions:
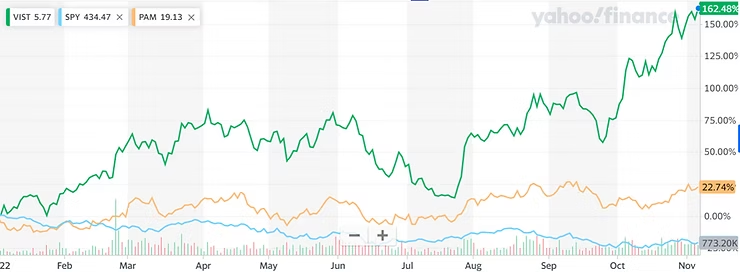
Vista's stock performance during 2022 was impressive, rising 160% year-to-date vs a 20% drop in the S&P 500. A crazy difference.
Can it keep going up?
Vista is a very young company (created in 2017) with a market cap of just 1,200 million USD... so it has a lot of room to keep growing, particularly considering that:
It currently exports 50% of its production.
Worldwide demand for oil and gas doesn't look like it will shrink in the short to medium term.
The new pipeline will let it export more.
It has been increasing the profitability of its oil wells, its sales and its net earnings in an impressive way.
We said the stock had risen 160% year-to-date, which seems a small number considering oil exports grew +446% YoY and net profit 325% YoY in the third quarter of 2022.
The company looks cheap relative to a fundamental multiples analysis and to a DCF analysis as well, based on the free cash flow reported by the company. It also has very good management. Although it may be a bit overbought in the short term — it is currently trading well above its 50- and 200-day moving averages — everything would indicate that in the medium to long term the company should keep growing at healthy rates.
If you are already a client of mine you probably already have Vista in your portfolio and are already enjoying the rise it is having... But if you don't yet have the stock in your portfolio, I think it is not a bad time to get in. Unfortunately we will never nail the exact moment to buy. So, I recommend getting in now and that's it. If you buy and it drops a bit, then it will be time to buy more!
As Warren says: "Picking bottoms is not our game. Pricing is our game. And that's not so difficult. Picking bottoms is, I think, impossible." We never think: is the market going to drop? Will we be able to buy cheaper? We don't know what the market will do. If we like something, we buy it. If the next day it drops in price and we have money, we buy more. Nailing bottoms is impossible.
Recommendation: BUY.
MB – 11/6/2022. Share price – 14 USD
Financial Advisor · Author · Columnist