Equities · Argentina
Pampa Energía: An extremely interesting investment possibility.
Miguel Braun · Nov 15 2021 · 7 min read
What is Pampa Energía?
Pampa Energía is a leading company in the Argentine energy industry, focused on electric generation and natural gas production, also a regional reference for its operational excellence and financial resilience. Pampa is an integrated energy company, generating and transmitting electricity, and also producing and transporting oil, natural gas and petrochemical products.
In 2020 they were the largest private electric generator in Argentina, representing 12% of total national generation, operating 15 generation plants, several of them renewable energy. During that year it was also the first time Pampa exported crude oil, and in both 2020 and 2021 they were exporting natural gas to Chile.
The company also has shale reserves in the Neuquén basin from the Vaca Muerta formation. Pampa has a dominant position in the petrochemical products market, since its products represent more than 85% of total sales in this market.
Other businesses Pampa has are its equity position in Transportadora Gas del Sur (27% of shares) and in Transener (26% of shares). TGS is the country's largest gas transporter, with 9,231 km of pipelines. It transports 60% of the country's gas and exports 33% of its production. Transener, in turn, operates and maintains 85% of Argentina's high-voltage transmission grid, with 21 thousand km of lines. Pampa also directly owns 28.5% of Refinor.
Pampa Energía's management is also excellent, which earned it entry in December 2018 into the special stock market trading panel called Panel +GC. Additionally, it's constantly running share buyback programs, because they consider the value of Pampa Group's assets is greater than the company's market price.
During 2020 they bought back 11% of the original equity capital and 10% of international notes. The company has been buying its shares for some time, and just since 2019 it has launched buyback plans for USD 150 million. They currently maintain a buyback program activated if the ADR trades below $15.50, or ARS 110 for local shares.
On to the numbers:
On November 10, 2021 Pampa released results for the quarter ended September 30, 2021. At closing prices of 11/12/2021, the company has a market cap of USD 1.028 billion and has 805 million in PP&E (property, plant and equipment) plus another 356 million only in stakes in other businesses. If you liquidate all of the company's assets, you have enough to buy all shares, pay all debt and have 223 million left over (Total assets – Enterprise value).
This leftover money can be considered a "margin of safety", a term invented by Benjamin Graham in the 1920s, considered the father of Value Investing. According to Ben, if you can buy a stock at a price less than the company's intrinsic value, that difference between what you pay (market cap) and the true value of the company leaves you with a margin in your favor that limits your risk and aims to maximize your gains.
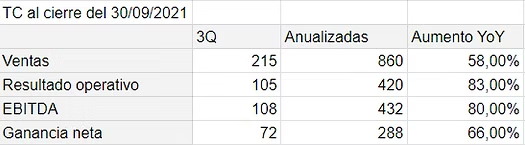
Having done this analysis, the result tells us Pampa Energía's sales in Q3 2021 grew 58% YoY measured in USD. Even better was the increase in net earnings, which were 72 million USD in Q3 alone, representing 66% YoY growth. These impressive results are explained by higher crude, gas and petrochemical prices, a strong increase in physical volumes sold across all businesses and more fuel sales for own thermal generation units.
International context: Pampa has been benefiting from the global oil and gas price rise, which should hold in the medium term due to the large hydrocarbon demand in Europe and the US during winter.
National context: Pampa Energía's results are impressive in themselves, but even more so being an Argentine company having to deal with the tremendous economic crisis the country has been living for years. This includes heavily reduced economic activity, inflation, devaluation, capped tariffs, high financing costs, very expensive taxes and everything else we know. Even so, the company manages to prosper and grow impressively.
In Argentina, many of the bad news are already priced in. Politically, winds of change may come in the short term. My opinion is if we ever do things moderately well, Argentine assets and Pampa shares can be worth much more.
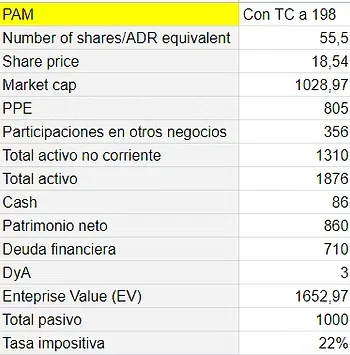
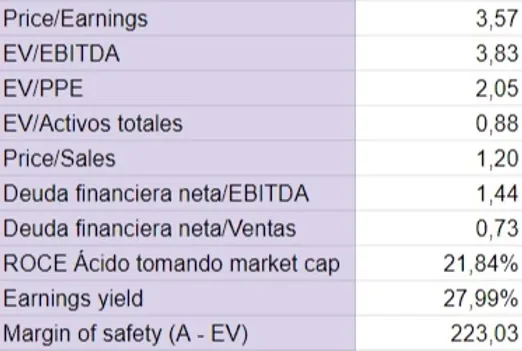
Besides accelerated sales and earnings growth, Pampa has another very interesting thing: return on capital employed or ROCE. The company invests capital and gets a 22% annual return on it in USD, a really impressive number. This in the long term, reinvesting its earnings, makes it an authentic compounding machine, as Benjamin Graham would say.
A company like Pampa Energía could easily trade at 7/8x earnings. If it did, that would give 95% upside in stock value and leave us with a price target in two years of 36 USD per ADR. Pampa Energía shares trade in pesos and in USD cable via its ADR. If you buy in pesos, having an ADR, if the USD cable rises and the USD stock stays the same, the peso price follows the dollar rise.
Recommendation: Mega strong buy.
For any additional information, contact me.
Financial Advisor · Author · Columnist