Argentina · Energy
YPF: The new Argentine crown jewel
Miguel Braun · Nov 8, 2024 · 5 min read
Dear all, good afternoon.
I'm writing this time because this week several companies reported results — Banco Galicia, Pampa Energía and YPF — posting very good results.
Where do we stand?
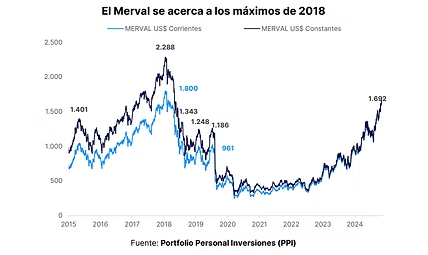
"The Merval reached a new high. This is the phrase repeated in our reports daily, as the index is on an unstoppable rally approaching the 2018 highs. It should rise an additional 6% to reach the highest nominal level of January 2018 (US$1,800). However, if we consider inflation in dollars, it still has room to grow. In constant terms, the 2018 high represents US$2,288 at today's prices. Therefore, to reach this high, the Merval would have to climb 35% above yesterday's closing level. This, without considering the structural differences in some sectors such as Oil & Gas or the growth of the banks that make up the index, which would allow an even larger Merval rise."
Also, with Trump's victory the dollar strengthened worldwide... but in Argentina it kept falling, and the spread is now near the lows of the Milei era. This tells us the freeing of the FX market is right around the corner and could arrive much sooner than thought if there is a disbursement of fresh funds from a multilateral organization like the IMF, a likely scenario given the good Trump–Milei relationship.
Other data about Argentina that surprised me from a talk I heard the other day by Claudio Zuchovicki:
- 50% of the Argentine population is under 30!!
- Argentines have 290 billion USD declared abroad and all listed Argentine stocks together are worth just 95 billion!!
I wanted to find the video of the talk to attach it because it really is worth it, but I couldn't find it again.
The crown jewel of the market:
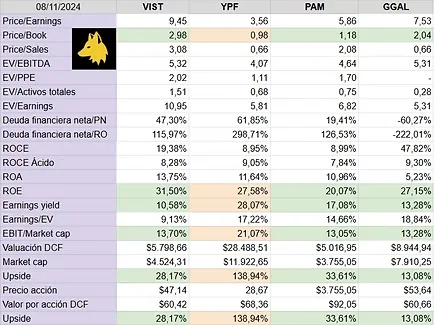
Comparing the results reported by all the companies, I can compare each one's valuation to know which ended up most expensive or cheapest. In this sense, the company that ended up cheapest and that my analysis gives the most upside to is YPF.
This is impressive: YPF trades at 1x its net worth, which means that if you take all the assets and pay all the liabilities, the value left is what YPF is worth at market today. This is because, despite the stock rising in price, the company's net worth grew 14% quarter over quarter, while its liabilities fell 2% in the same period. This is the best possible explanation of why stocks go up: because companies increase their net worth! Banco Galicia and Pampa Energía were doing the same thing, for example.
That is, the company trades at the same value at which it could be liquidated, but also:
- It has been earning 28 USD for every 100 you pay to buy the stock today, being the Argentine company with the best earnings yield right now, or equivalently, the lowest price/earnings ratio.
- It increased its profit 368% comparing the first 9 months of 2024 vs the first 9 months of 2023, and 178% vs Q2 2024, thanks to a tax benefit. Even if we remove this tax benefit, it increased its operating result 28% quarter over quarter. Very solid.
- Doing a DCF valuation for all companies, assuming 0% growth in future earnings for the next 20 years and discounting these future flows at 10%, I get that the company should be worth more than double what it's worth now. It's the one with the most upside in this regard, having used the same growth and discount-rate assumptions for all companies.
- It also has: a consolidated brand, know-how, concessions, oil wells, a thousand service stations across the country, firm export contracts; they are swapping short-term debt for long-term debt at almost no financial cost and many other positives.
- Shale oil production grew 36% in the third quarter, averaging 126,000 barrels per day, a 36% increase vs the same period of the previous year and 11% vs the second quarter of this year. Today it represents 49% of YPF's total oil production (Q2 24: 46% and Q3 23: 39%).
- Medanito oil exports increased 111% in the quarter vs the third quarter of the previous year and 37% vs the prior quarter. Exports averaged 39,000 barrels per day, 15% of total oil production.
Progress of YPF's main projects:
Andes Project: 9 sale-and-purchase agreements have already been signed for 25 areas. Recently, 7 areas located in the province of Tierra del Fuego were added. Provincial approval was also obtained for one of the clusters in Chubut.
This is good: the company is shedding mature conventional wells to focus on the unconventional ones, which are more profitable.
Vaca Muerta Sur pipeline construction project: 50% progress was reached in the construction of the first section (Vaca Muerta – Allen, 130 km), with a total investment of approximately USD 200 million. The second section consists of a pipeline dedicated to exports (Allen – Punta Colorada, 440 km), storage tanks and single-point moorings to operate VLCCs, with an investment of around USD 2.5 billion. The company is a few months from starting its construction.
Conclusions:
YPF has been investing heavily in these and other projects, to expand its production and the transport capacity for it, so it can export more and more.
The energy sector in Argentina is in full growth and is, in my view, THE most attractive sector to invest in right now, also because it is a very defensive sector: people are going to keep consuming oil and energy for the rest of their lives.
Within this sector, YPF is the great leader. Besides being the highest-value company right now, it is also the one with the most areas in Vaca Muerta and the one that will lead all the big projects and investments coming up.
Recommendation:
Given the differences in valuations, YPF is TODAY the most attractive Argentine company to buy right now according to the numbers and fundamental analysis.
That is why it gets a STRONG BUY recommendation.
For those who have Vista in their portfolio, next week I'll be swapping Vista shares for YPF shares for all those who have read the report and reply telling me they are up for the switch!
The relative valuation of both companies tells us that today YPF is cheaper and at these prices more profitable than Vista, so I think it is good to swap one for the other and thus buy more YPF.
Today the first stage of the tax amnesty ends, and that is why we are seeing a perfectly healthy correction in many Argentine stocks. I think we still have a lot ahead, since we haven't yet reached the inflation-adjusted 2018 highs, and Milei's government is doing everything right. We have everything to keep growing and finally get out of the hole we ended up in after years of populism, Peronism, Kirchnerism and socialism. I'm more optimistic than ever; the valuation of Argentine companies is still very cheap because companies back the rise in their stocks with growth in their earnings and net worth.
That's all for today, I hope this information is useful.
I send you my regards and wish you a good weekend!
Miguel
Financial Advisor · Author · Columnist