Global · Industry
TX (Ternium): Value play — A good opportunity
Contents
Miguel Braun · Nov 5, 2022 · 5 min read
Ternium is a leading company in the manufacturing and processing of a wide range of steel products. With 18 production centers in Argentina, Brazil, Colombia, the United States, Guatemala and Mexico, they manufacture highly complex steel products that supply the region's main industries and markets.
The steel produced by Ternium is used in several different industries:
· Construction: At Ternium they manufacture high-quality products to supply housing and infrastructure works. Present in the roofs of houses and factories, in the mezzanines of buildings, and in the insulating walls of the most modern offices.
· Energy: Steel is essential in all energy sectors, both fossil and nuclear and renewable. Ternium offers materials that withstand high demands without their performance being affected, often in extreme climatic and geographic circumstances. They are also present in the extraction and distribution process of unconventional hydrocarbons, in nuclear plants and hydroelectric power stations.
· Transport and automotive: Steel is the ideal material to meet the needs of the automotive industry because it is light, versatile, resistant and economical. In addition, many components of trains, ships and planes, as well as tracks, tunnels, bridges, and even charging or service stations use the steel produced by Ternium in various forms.
· White goods: Ternium products are used for washing machines, air conditioning equipment, electrical cabinets, water heaters, refrigerators, ovens and much more.
· Agro-industry: The agricultural industry needs steel for its processes and services, since it is used to manufacture equipment and tools, preserve and transport harvests, among other uses and applications.
Steel trends and shipments by country:
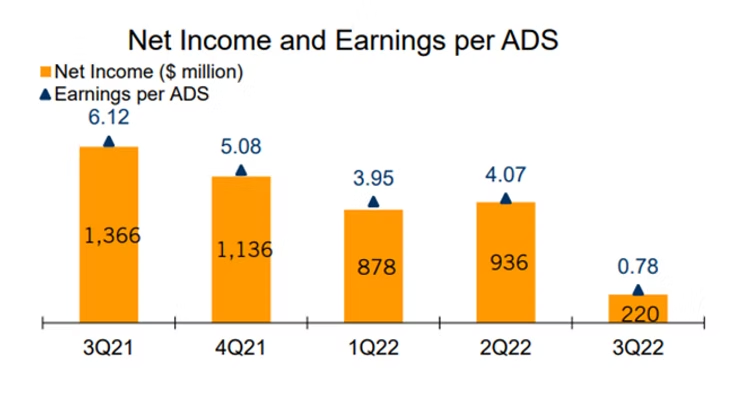
Although steel shipments remained relatively stable during 2022, the price of steel fell quite a bit, which was affecting the company's net profit, which has been declining. This may be one of the reasons the company is trading so cheap (as we will see below).
All that the company has in cheapness is what it lacks in momentum. But it is not bad to buy now. The company keeps making a lot of money; if we are going to wait for steel prices to recover, the price we will pay to become a shareholder will be much higher.
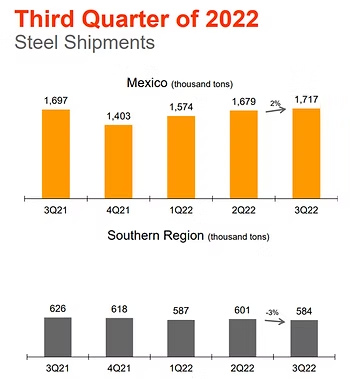
58% of Ternium's sales are in Mexico:
The drop in steel prices and the increase in production and material costs used to produce caused net profit and EBITDA to fall this quarter:
Dividend:
Ternium's board of directors approved the payment of an interim dividend of $0.09 per share ($0.90 per ADS), or $176.7 million in aggregate. The dividend will be paid on November 17, 2022 to shareholders of record as of November 15, 2022. This interim dividend proposal reflects the company's solid financial performance so far in 2022, the strength of its balance sheet and its positive outlook for cash generation going forward.
Let's go to the numbers — why does it represent a good opportunity?
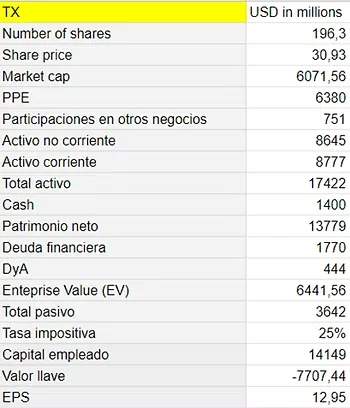
With a market cap at market close prices of 11/4/2022, the company is worth 6,071 million USD.
In current assets alone the company is worth 8,777 million USD, and it has total liabilities of 3,642 million USD. That is: the company trades below its liquidation value!
Benjamin Graham in "The Intelligent Investor" said that a company's liquidation value can be calculated as current assets minus total liabilities. This is because liabilities are always real, while assets are sometimes inflated. So by doing current assets minus total liabilities you could get an idea of what the company's liquidation value is. In this case if we liquidate the company using only current assets to pay all liabilities, we still have 5,135 million USD left over.
Graham called these types of stocks net-nets, and they are very hard to buy. Generally stocks that trade so cheap are because they have debt problems, or are losing money. That is not the case with Ternium, whose business brings excellent results.
So the company trades:
- Below the value of its current assets
- Below the value of its net worth (book value)
- It has no debt problems
- Plus it makes a lot of money and has excellent returns on capital employed. The company trades at 0.44 times book value, 2.80 times earnings and also has an earnings yield (earnings/market cap) of 35%. That is: you pay 100 USD to become a shareholder, the company earns 35... Even in a "bad" year like 2022 has been. In 2021 that ratio at the current price of the company is 63 USD for every 100 you pay to become a shareholder, crazy.
It also pays a dividend of almost 9% a year, and if you buy it now you collect a dividend of 2.9% that they will pay on November 17. Not bad...
The bad thing, as we said before, is that the company is having a bad year compared to 2021 due to the increase in its production costs and the reduction in the steel price. This makes the analyzed ratios decrease relative to 2021. But seeing that shipments remain stable, I think this doesn't represent a problem for the company at all. I prefer to buy it when the steel price is cheap, this way the price we pay to become a shareholder will be lower.
DCF valuation:
We take the company's annualized FCF for 2022 — a bad year, remember — which is 1,625 million USD. In a conservative analysis we assume this FCF will never increase again, i.e., a 0% growth rate. Then we discount the flows at a 10% rate (as Warren Buffett does) and we get that the company should be worth 13,835 million USD. This would represent 128% upside over the current price. Not bad...
Conclusions:
The company is very cheap but also generates very good returns on capital employed and especially very good earnings relative to the price we are paying to become a shareholder.
The analysis resulting from the multiples and DCF valuation tells us the company undoubtedly has the "margin of safety" Warren Buffett recommends when investing. This limits our downside potential (how much cheaper can it get?) while maximizing our upside potential, which is undoubtedly a path to success.
Recommendation: BUY
"Price is what you pay, value is what you get"
MB - 11/5/2022. Share price - 30 USD
Financial Advisor · Author · Columnist